Federal Reserve Governor Lisa Cook isn't backing down. Facing a renewed push from the White House to force her off the central bank's board, Cook's legal team fired back with a sharp response, calling mortgage fraud allegations completely unfounded.
If you've been following this high-stakes clash, you already know the underlying friction. President Donald Trump wants lower interest rates. The Federal Reserve hasn't moved fast enough to satisfy him. Removing Cook would give the administration a majority vote on the board. It is a transparent power grab disguised as a paperwork dispute.
Let's look at what is actually happening behind the headlines.
The Mortgage Claims and the Paperwork Reality
The White House argument centers on real estate filings from 2021. Officials claim Cook improperly listed multiple properties—specifically a home in Ann Arbor, Michigan, and a condominium in Atlanta—as primary residences. The administration argues this classification could theoretically secure better loan terms.
Cook's attorneys, Abbe Lowell and Norm Eisen, didn't mince words in their reply. They pointed out a glaring double standard. They noted that the president himself and several members of his own cabinet have navigated identical paperwork mix-ups on real estate documents. An accidental clerical error on a standard mortgage form does not equal fraud.
Furthermore, independent analysis of Cook's financial disclosures shows she actually categorized the Atlanta property as a vacation home or second home on separate, official federal filings. True fraudsters don't accidentally leave a trail of accurate disclosures across different government agencies.
Why Central Bank Independence Matters Right Now
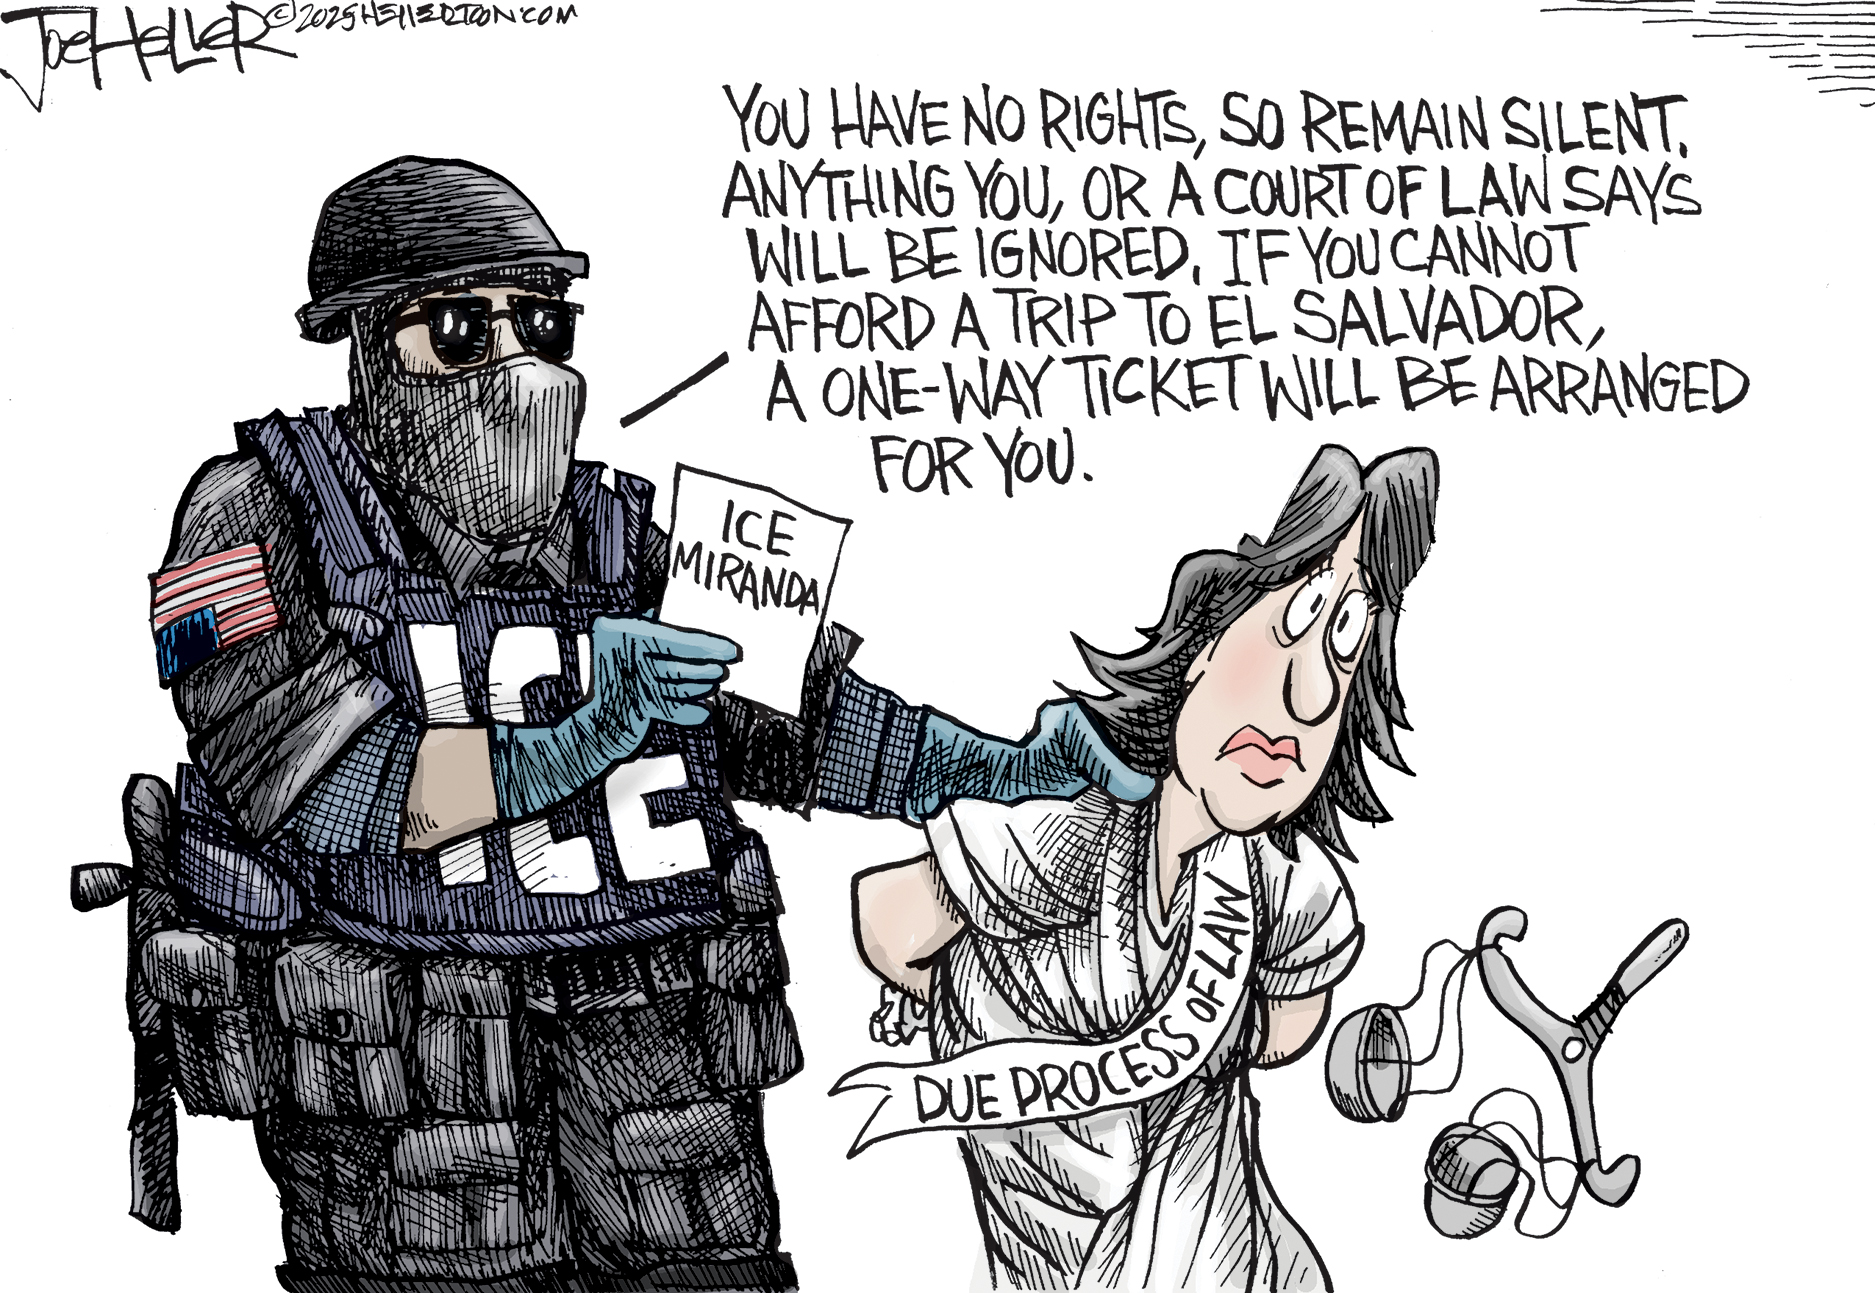
The Federal Reserve is designed to act as an independent economic steering wheel. Congress set up fixed terms for governors precisely to insulate monetary policy from short-term political whims. If a president can manufacture cause to fire a governor over minor administrative paperwork, that independence evaporates.
Think about what happens next. If central bankers worry they will lose their jobs every time they disagree with the executive branch on interest rates, monetary policy becomes politicized. Economic decisions stop being driven by inflation data and employment numbers. Instead, they start bending to election cycles.
The Supreme Court already blocked an earlier attempt by the administration to oust Cook, ruling that the president cannot dismiss a Fed governor without legitimate cause. Yet the White House keeps pushing, utilizing administrative pressure and deadlines set by aides like Dan Scavino to test the legal boundaries.
What to Watch As This Battle Continues
This fight is far from over. The legal friction highlights a broader tension between executive overreach and institutional safeguards. Cook remains on the board, protected for now by the courts, while the underlying legal framework protecting the central bank faces its toughest test in decades.
Expect more administrative filings, aggressive public statements, and intense scrutiny on every move the Federal Reserve makes regarding interest rates. Keep your eyes on the legal briefs, not the political distractions. The future of monetary independence hangs in the balance.